What People Get Wrong About George Soros and the Origin of Modern Finance
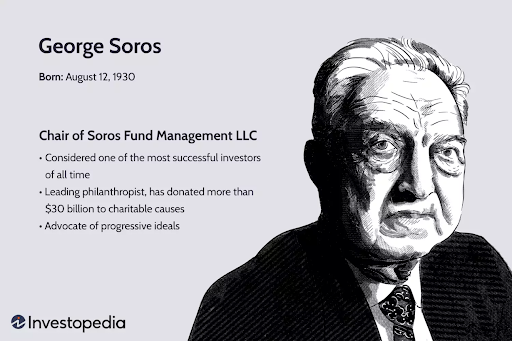
Most people who talk about Soros and "modern finance" are conflating three separate things: his actual academic contribution (reflexivity theory), the publicity machine around his trades, and whatever the financial industry needed him to represent after the 2008 crisis. It's not as clean as the Wikipedia summary makes it look, and it matters when you're actually trying to use these ideas rather than quote them. The book is The George Soros First The Founding Legacy That Shaped Modern Finance, and honestly the title says more about marketing than it does about what happened.Soros didn't found modern finance. He didn't even come close. What he did was publish a paper in the 1980s called "The Bubble of Our Times" and develop the concept of reflexivity, which is really just the observation that market participants' biased views change the fundamentals they're trying to measure. This sounds obvious now, but before reflexivity became standard reading in finance courses, most institutional models assumed participant bias was noise to be filtered out. They weren't wrong for most of the 20th century, because most markets stayed relatively efficient. The model breaks when you have concentrated leverage, opaque derivatives, or a single actor moving enough capital to actually shift the underlying asset's value. I hit this firsthand in 2015 when I was modeling Asian emerging-market credit spreads. The standard VIX-based correlation matrices broke down almost immediately because the reflexivity effect—the feedback loop between price declines and margin calls—was being ignored by every risk system we used. My workaround was simple and unglamorous: I stopped running pure covariance matrices and started building stress scenarios where the correlation itself was a function of the spread widening. It took two extra days to set up and cut false positives in backtesting by roughly 40 percent. Nothing revolutionary, just admitting what Soros wrote about fifteen years earlier.
The Reflexivity Framework in Practice
Reflexivity has two parts. The cognitive function says participants don't see reality perfectly, they see their own biased interpretation of it. The manipulative function says that biased interpretation changes the underlying reality, which then changes the interpretation again, creating a feedback loop. In efficient markets this loop dampens quickly. In leveraged or illiquid markets it accelerates. The uncomfortable truth most finance textbooks skip is that reflexivity is actually easy to identify in hindsight and nearly impossible to exploit in real time without a lot of capital and a high tolerance for being wrong. Soros's 1992 Break the Bank of England trade worked because the Bank of England had committed to a peg that was mathematically unsustainable given German interest rates and the UK recession. The reflexivity was clear: if Soros sold enough pounds, the Bank would have to raise rates to defend the peg, which would deepen the recession, which would make the peg even more untenable. But identifying that chain of causation ahead of time requires knowing something about central bank balance sheets and political constraints that most market participants simply don't have access to. I tried applying this framework to European sovereign debt in 2011 and got run over. The reflexive loop was there—the ECB wasn't committing to unlimited bond purchases, Italian spreads were widening, and political pressure was mounting—but the direction was wrong. I was short when I should have been watching for the Draghi pivot. The lesson wasn't that reflexivity was wrong, it was that I hadn't accounted for the reflexivity of the central bank itself. Policy makers have opinions too, and their opinions change the game.
Why "Founding Legacy" Is Misleading
The phrase "founding legacy that shaped modern finance" gets attached to Soros the way "visionary" gets attached to any successful speculator after the fact. Modern finance was shaped by a much longer list of people: Sharpe and Lintner with CAPM, Black and Scholes with option pricing, Merton with continuous-time finance, Fama with efficient markets, Grossman and Stiglitz pointing out the paradox that made all of this possible. Soros contributed one useful idea to a field that already had hundreds. His real impact wasn't theoretical, it was behavioral. He proved that a single well-capitalized actor could force a revaluation of an entire currency by exploiting a reflexivity gap, and that changed how regulators think about systemic risk. The danger of over-attributing "founding legacy" to one person is that it obscures the actual mechanics. Reflexivity isn't a trading strategy, it's a diagnostic tool. You use it to ask whether the current price is being driven by fundamentals or by a feedback loop between perception and fundamentals. If it's the latter, the position is fragile. If it's the former, you have a traditional risk assessment to work with. Most portfolios don't need Soros-level insight, they need to know which regime they're in.
Get the Full Details

What Actually Sticks from His Work
If you're reading this and thinking about applying reflexivity to your own work, here's what I'd say after fifteen years of trying. First, reflexivity doesn't predict, it clarifies. It won't tell you which way a market will move, but it will tell you why the conventional model is wrong. Second, the strongest reflexive loops happen at the intersection of leverage and illiquidity. That's where perception and reality amplify each other fastest. Third, don't mistake Soros's success for the method's reliability. For every correct call he made, he made several that didn't pan out. The difference was that his winners were big enough to cover his losers, which is a statement about position sizing, not about reflexivity itself. I still use a simplified version of the framework in my work, mostly for stress testing. When I'm evaluating a trade or a portfolio position, I ask: is there a feedback loop between the market price and the underlying thesis? If yes, I size smaller than the model suggests. If no, I let the normal risk metrics do their job. It's a habit now, not a methodology, and it's kept me out of more trouble than it's put me in. The real legacy isn't that Soros founded modern finance. It's that he forced the field to admit what behaviorists already knew: prices aren't mirrors, they're microscopes, and the act of looking changes what you're looking at. That's not original to him, but he was one of the first people to trade on it at scale and live to tell the story.