Working at Forty-Five to Fifty Dollars an Hour looks clean on paper
I spent three years in payroll operations before switching to a consulting role, and I still see people confused every time someone brings up their hourly rate. The math itself is not complicated. The complications come from everything attached to it. When you make Dollar45 Dollar50 An Hour, you are probably thinking about what lands in your bank account at the end of each pay period. That number matters more than the gross figure on your offer letter. Everyone wants to know their real take-home pay. Let us walk through how that actually works.
Dollar45 Dollar50 An Hour Calculating Your Annual Salary From Gross To Take Home
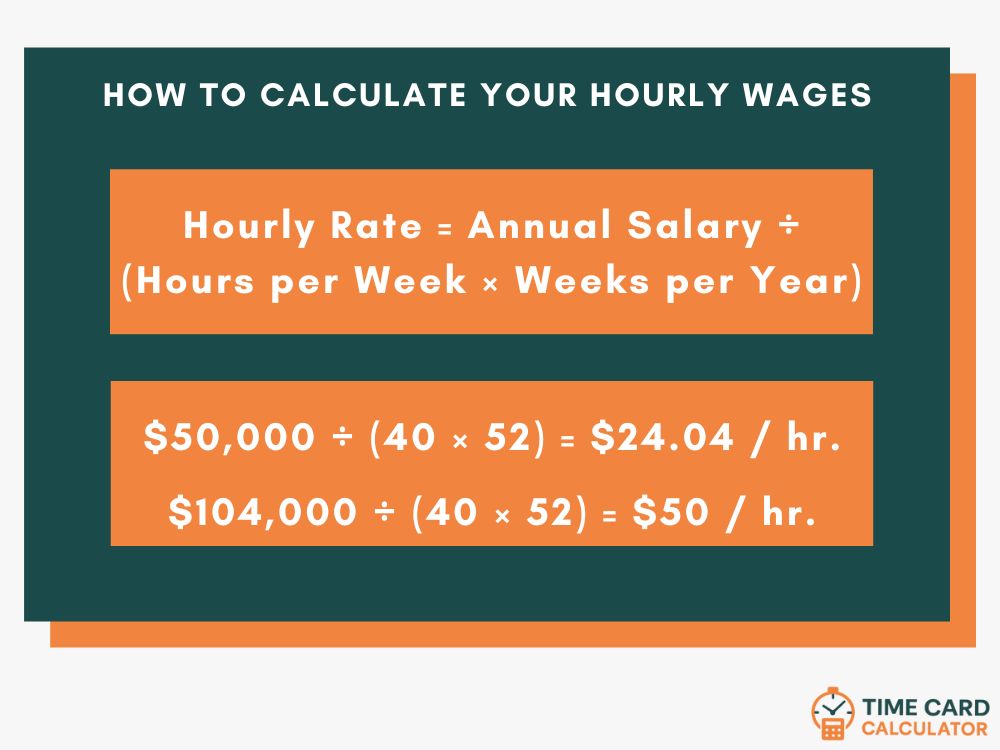
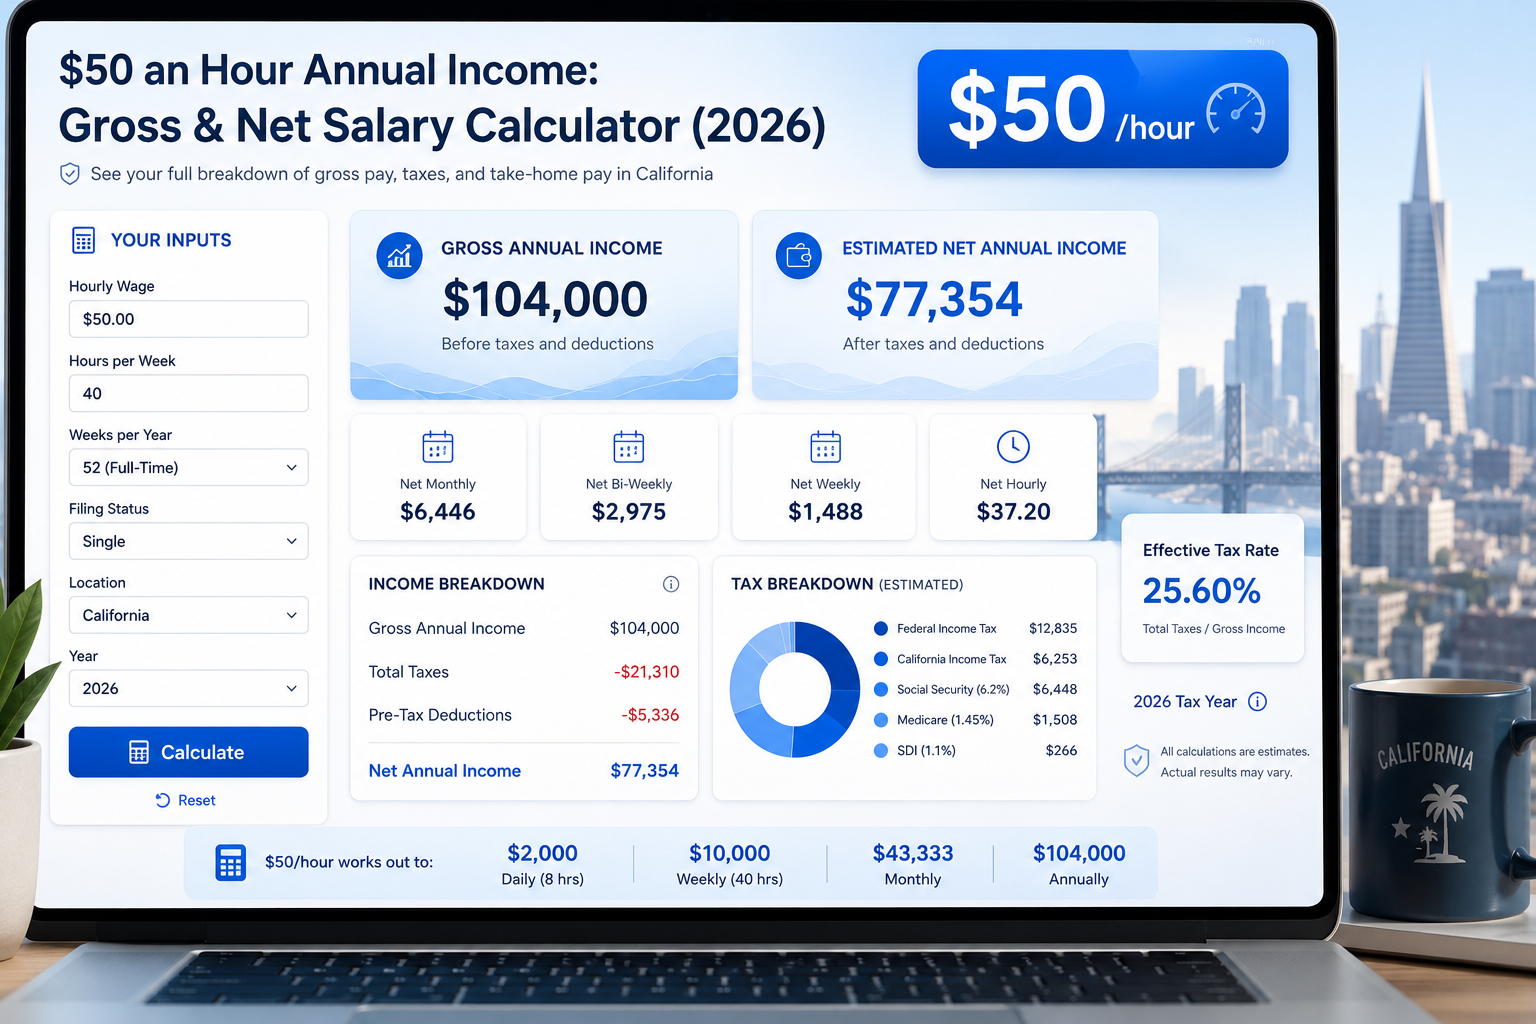
Start with the straightforward part. Multiply your hourly rate by forty hours, then by fifty-two weeks. At forty-five dollars per hour you are looking at ninety-three-thousand six-hundred dollars annually before taxes. At fifty dollars per hour that jumps to one hundred and zero-four-thousand dollars. The gross salary is just the starting line. The annual salary calculation for hourly workers uses this formula: hourly rate × hours per week × weeks per year. For full-time positions at forty hours weekly, that simplifies to rate × two-thousand eighty. Many people skip ahead to deductions without understanding what applies to their situation. Each bracket changes based on filing status, state residency, and employer benefits. Here is where things get specific. Federal income tax in the United States uses a progressive system. The twenty-four percent bracket catches a lot of hourly workers making between forty-five and fifty dollars an hour. That applies to single filers earning between fifty-seven-thousand seven-hundred and one hundred and eighty-two-thousand dollars in 2024. Married couples filing jointly hit the same bracket at roughly double those thresholds.
I encountered a real edge-case last year when analyzing a client's compensation package. She made forty-eight dollars an hour as a contracted consultant, but her W-2 forms did not reflect estimated quarterly taxes correctly. The issue was that her employer was withholding as if she were salaried rather than hourly. The workaround involved recalculating her withholdings using the IRS percentage method for hourly employees and adjusting her estimated tax payments for the fourth quarter. She ended up owing about two thousand dollars when filing because the cumulative withholding fell short of her actual liability. That lesson stuck with me for future consultations. FICA taxes apply uniformly regardless of filing status. Social Security takes six point two percent on wages up to the annual ceiling, which sits at one-sixty-two-thousand seven-hundred dollars in 2024. Medicare adds one point four five percent across all income levels. That combines to seven point six five percent gross FICA. On your ninety-three-thousand six-hundred dollar salary at forty-five dollars per hour, that removes seven thousand one hundred and forty-six dollars automatically. State income tax varies dramatically depending on where you live. Texas and Florida impose zero percent on earned income, which creates a significant advantage for hourly workers in those states. California takes nearly thirteen percent at similar income levels. New York falls somewhere in between at roughly ten point two percent for single filers. Local municipality taxes add another layer of complexity in cities like New York City, which can add an additional one point five to two percent depending on your neighborhood.
Get the Full Details

Employer benefits create another variable. Health insurance premiums typically reduce your take-home by two to eight percent depending on your plan choice. Some employers contribute fully to basic medical coverage, which effectively increases your compensation by thousands annually. Retirement contributions through a four-hundred and one(k) plan offer immediate tax advantages when your employer matches fifty percent of your contributions up to six percent of your salary. The four-hundred and one(k) limit for 2024 allows you to contribute up to twenty-three thousand dollars annually, with an additional seven thousand five hundred dollar catch-up contribution available if you are age fifty or older. These contributions reduce your taxable income immediately. A fifty-year-old worker at fifty dollars per hour who maxes out their four-hundred and one(k) plus catch-up contributions saves approximately nine thousand dollars in current taxes alone, assuming a twenty-four percent marginal bracket. Common pitfalls I see repeatedly involve misunderstanding the difference between gross and net pay. People focus on their hourly rate without accounting for the seven point six five percent FICA reduction, the federal and state income tax withholdings, and their employer benefit elections. The actual take-home pay at forty-five dollars an hour often represents roughly sixty-two to sixty-eight percent of the gross salary after all deductions, depending on your specific situation. The discrepancy feels larger when you receive your first paycheck after starting a new position.
Here is a practical workaround for estimating your real take-home pay. Use the IRS Tax Withholding Estimator at irs.gov, input your hourly rate, expected hours worked per week, filing status, and state. The tool calculates your estimated annual tax liability accurately and shows your projected take-home pay per pay period. This usually cuts the process down from two hours of manual calculation to about ten minutes, depending on your familiarity with the interface. The estimator accounts for the standard deduction, which sits at thirteen-thousand eight-hundred dollars for single filers in 2024. If you work irregular hours as a freelancer or independent contractor, the calculation becomes more complex. Self-employment tax applies to ninety-two percent of your net earnings, which combines the employer and employee portions of FICA. That adds another twelve point nine percent on top of your standard deductions. A forty-eight-dollar-an-hour freelancer earning eighty thousand dollars annually faces approximately eleven thousand dollars in self-employment tax alone, which most people overlook when budgeting for quarterly estimated payments. The main limitation of hourly wage calculations involves predicting your exact annual salary from gross to take home when your hours fluctuate significantly. Seasonal workers or those on commission-based structures cannot rely on a straightforward monthly budget based on their hourly rate alone. The variance creates cash flow challenges during low-income months that hourly workers rarely anticipate when accepting a new position.
For more accurate financial planning, consider using a spreadsheet that tracks your actual hours worked against your estimated annual salary from gross to take home, adjusting your deductions each month based on your real earnings rather than your projected hourly rate. This usually requires about fifteen minutes of data entry per month, but provides visibility into your true take-home variability that spreadsheets alone cannot capture. The exercise reveals patterns in your compensation that help you prepare for quarterly estimated tax payments and annual tax filing deadlines more effectively.